
Why We Can’t Soak the Rich

Today we continue my series on debt and taxes. In brief, the federal government has a huge amount of spending, a less huge amount of tax revenue, and thus a huge debt. Almost everyone agrees we need to close this gap. We differ on how to do so.
A Quick Look at Social Security
Thanksgiving in Tulsa, Las Vegas, Cleveland, NYC and Austin
Today we continue my series on debt and taxes. In brief, the federal government has a huge amount of spending, a less huge amount of tax revenue, and thus a huge debt. Almost everyone agrees we need to close this gap. We differ on how to do so.
Last week we looked at just income taxes. This week we are going to look at other types of US taxes as necessary groundwork for when we look at what the outcome of raising various taxes will be, either with or without accompanying spending cuts. Then we will start on how effective simply raising taxes will be. I expect that to be at least one if not two more letters.
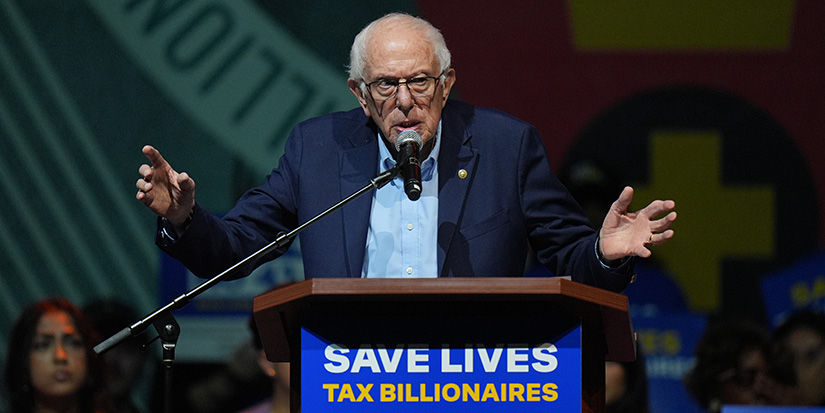
There are two knobs we can turn: more/less spending and more/less taxes. We can turn one of them, both of them or neither of them. Specifically, can we make a dent in the debt by raising taxes on the wealthiest taxpayers? That’s politically appealing to some because it leaves most voters unaffected, though it may affect the economy by reducing growth as it has elsewhere. That being said, there is serious research that shows taxes can raised somewhat without too much drag on the economy, but nowhere near enough to solve the problem.
The problem with simply taxing the rich more, as you’ll see, is that it won’t solve the problem, because it changes behavior and thus eventual taxes. The debt will still be there and the voters we are trying to shield will still get hurt.
A Quick Look at Social Security
I will go deeper on Social Security in a future letter. It deserves more than a short mention. But since payroll taxes are a giant part of all federal revenue – and Social Security benefits comprise a giant part of federal spending – I want to run through a few preliminary numbers now.
Social Security at a Glance

Because of the wage cap, the payroll tax is a flat tax up to $184,500 and zero above it. That makes it regressive at the top, which is exactly why "raise the cap" is always on the list of fixes. We will run those numbers when we get there.
Up to 85% of benefits can be subject to income tax for retirees above certain income thresholds. The tax on the first half of benefits goes back into the Social Security trust funds, about $58 billion in 2025; the tax on the portion between 50% and 85% goes to Medicare's hospital insurance fund. The income thresholds have not been adjusted for inflation since 1993, so every year more retirees get caught. This has quietly been propping up the trust funds. (See, sometimes inflation helps! – note sarcasm) The new senior deduction in last year's tax bill further reduced Social Security revenue, though temporarily as the $6,000 tax break expires in 2028.
Overall, the system’s costs have exceeded its tax revenue since 2010 and exceeded total income, including interest, since 2021. The trust fund is not a vault. It is an IOU from the Treasury, and the Treasury has to borrow to redeem it. As I said, this will take a full letter, because they’re just 100 nuances. There are almost 60 million Americans receiving Social Security.
The total Social Security beneficiary population (all ages) is over 76 million people in October 2026, but the vast majority are older adults. Most paid Social Security taxes for their entire adult lives and have the entirely reasonable expectation that they will get those benefits when they retire.
According to the U.S. Census Bureau’s analysis of survey responses matched with IRS tax and Social Security Administration benefit records, about 14%, or 22 million, older Americans receive 90% or more of their household income from Social Security. Survey data, which is subject to the vagaries of survey questions, suggest that the number might be as much as twice that. There are reasons for this discrepancy, and we will walk into that minefield in a later letter.
Corporate Tax Rates
The corporate income tax is a much smaller part of the picture than its political profile suggests, amounting to only about 7% of federal revenue last year. The 2017 tax law cut the rate from 35% to 21%. Here is what happened to receipts.

Receipts fell sharply in the first three years after the cut, as everyone expected. Then they climbed to records: $425 billion in fiscal 2022 and $530 billion in fiscal 2024, far more than the government ever collected at 35%. Supporters of lower rates point to this as evidence that a lower rate can bring in as much or more revenue over time, by keeping profits and headquarters in the US and reducing the incentive to shift income abroad.
There is research behind that view. Kevin Hassett and Alex Brill found a corporate "Laffer curve" across developed countries, with the revenue-maximizing rate drifting down toward about 26%; Kimberly Clausing's basic estimate was about 33%. Both were above the 21% we have now, and both were below the 35% we had before 2017.
On the other hand, the Congressional Research Service disputes those findings and argues that most of the post-2021 surge reflects inflation and unusually high corporate profits rather than the rate cut. And receipts fell to $381 billion in fiscal 2026, in part because last year's tax law restored full expensing for business investment. This requires a little deeper dive.
First, the law that allows businesses to deduct ordinary and necessary business expenses was first established in the Internal Revenue Code of 1954, and has been amended several times since then, most recently and significantly in 2017 in the first Trump administration. Going forward, the details matter if we are going to consider raising corporate tax rates again.
Prior to 2025, 100% bonus depreciation had been available under the 2017 Tax Cuts and Jobs Act (TCJA) for qualified property placed in service between September 27, 2017, and the end of 2022
The TCJA introduced a phase‑out: 80% in 2023, 60% in 2024, 40% in 2025, 20% in 2026, and 0% by 2027
The OBBBA restored the 100% rate and made it permanent for qualified property placed in service after January 19, 2025
This applies to most tangible personal property with a recovery period of 20 years or less, certain software, and other qualifying assets, allowing corporations to deduct the full cost in the first year instead of depreciating over time.
The purpose behind accelerated depreciation is to give businesses incentive to invest money sooner than they might otherwise. And it clearly works. And while it costs “tax revenue" to allow for earlier depreciation, over time it evens out. Let's say that a particular widget would normally depreciate over five years. It would be the same total deduction whether it is over one or five years, so over time, the revenues will equal out. But the theory is the economy is growing faster. The counterargument is that businesses will make the investment anyway. In some cases, this is very likely true. But not in all cases.
My own reading is that above some point higher corporate tax rates cost more in lost investment than they bring in, and that the 35% we had before 2017 was well above that point, one of the highest in the developed world. 21% is a great number as it makes us competitive with countries like Ireland that have lower rates. But could we increase it to 25% or some higher number? When we are raising taxes everywhere else because of the deficit and debt? If we are going to solve the debt crisis, everything has to be on the table.
Longtime readers will know that my default position is for lower taxes and smaller government. But in what I believe is the coming sovereign debt crisis, people of good faith on all sides are going to have to make compromises. And as I keep repeating, no one will like them. They will all be bad choices.
Here’s another look at a chart I shared last week. Note how the individual income tax and payroll taxes dwarf corporate income tax revenue.

Below the corporate tax are some even smaller categories: Tariffs, excise taxes (gasoline, etc.), estate and gift taxes, etc. These generate much more heat than they do money for the government. Even Trump’s new tariffs – which have caused real economic damage – are a rounding error in the big picture. They grew a lot in percentage terms, from $79.1 billion in FY 2024 to $194.9 billion in FY 2025. My preference would be to have a low and standard flat tariff if we have any tariff at all, rather than using tariffs as a hammer to bludgeon our trading partners. Are there cases can be made for a tariff? Yes, and they should be on the table.
Then there’s the estate tax. Very few estates actually pay it because very few estates are bigger than the excluded amount. The few that are bigger can usually avoid it by employing (perfectly legal) estate planning techniques. The estate tax is as close as we get to a “voluntary” tax. Anyone who actually pays it does so by default.
Now, About Taxing the Rich
We now have enough data to begin do the arithmetic. Let's first be generous to the idea and assume, unrealistically, that nobody changes their behavior. No one moves, no one realizes fewer capital gains, no one restructures a business or hires a better accountant. These are static numbers, using 2023 income against the 2026 deficit.
"Tax the Rich" vs. the Deficit (static estimates, no behavioral response)

Sources: IRS Statistics of Income via Tax Foundation (tax year 2023); CBO; Forbes; Mauldin Economics static calculations; Mauldin Economics, John Mauldin.
Read that table slowly. First note that the reason the top 1% only pay 26.3% of their income as taxes, is that much of their income is capital gains and other tax-favored income. They will pay the full 39.9% on their non-capital gain or tax-sheltered income. To get them to pay 40% you would have to exclude capital gains taxes above a certain number. Again, that assumes no behavior changes which is not realistic.
Raising the average tax rate on the top 1% by more than half, from 26.3% to 40%, which would require top marginal rates far above today's 39.9% (including the Medicare tax), raises about $430 billion on paper. That closes about a fifth of the gap. To close the whole deficit through the income tax on the rich, you would have to take essentially every dollar the top 1% earns, after what they already pay, and they would have to keep earning it anyway.

Wealth taxes don’t escape the arithmetic either. The Forbes 400 are worth a record $8 trillion this year. Seize all of it, every share of every company, and you could pay for about four years of deficits. Once. Then it would be gone, along with the companies those shares represent being run by people with every incentive to make them grow.
And those are the generous numbers. In the real world, behavior changes. Top incomes are dominated by capital gains, which people can choose when to realize. Top-end income is also volatile: in 2023 the income of the top 1% fell 9%, mostly because of lower realized capital gains. We have been in an extraordinarily powerful bull market which allows for extraordinarily high capital gains. A bear market will eviscerate those potential gains.
Raise the rate sharply and gains get realized less often, held until death, or moved into structures that are taxed later or not at all. The revenue estimates shrink. That is Adam Smith's fourth maxim in action.
Let me be clear about what I am and am not saying. I am not saying the rich cannot or should not pay more. There may be good arguments for some increases at the top, and we will look at them fairly. What I am saying is that "tax the rich" cannot, by itself, come anywhere close to closing a $2 trillion deficit, much less pay for new spending on top of it. The math simply doesn’t work. The people making that promise are either not doing the arithmetic or hoping you will not.
The Scorecard
Pulling the key numbers together in one place:

IRS figures are tax returns, tax year 2023. CBO figures are households, 2023, and include payroll, corporate and excise taxes. n/a: not published on that basis. Sources: IRS SOI; Tax Foundation; CBO; Mauldin Economics, John Mauldin.
The rich pay most of the income tax already. The middle pays mostly payroll taxes (which are quite real, especially in percentage of total income terms). The bottom 40-50% as a group is a net recipient of government subsidies as we demonstrated last week. And the income tax, whatever its top rate, has brought in roughly 7% to 10% of GDP for 75 years.
Next, we have to ask an uncomfortable question. Suppose we tried to get the deficit below nominal GDP growth using taxes alone. How much would we need to raise? From whom? Through what kind of tax? Since 86% of revenue comes from individual income and payroll taxes, any serious income tax-only plan has to reach deep into the middle class, or find another revenue source. For instance, the average OECD country gets 31% of their tax revenues from consumption taxes, either direct sales taxes or the much larger case of value-added taxes (VAT).
In future letters we will look at what various rate increases would actually raise, what the economic research says about the drag on growth, and why most of the developed world funds its welfare states with broad consumption taxes as well as payroll taxes and income taxes rather than by taxing the rich even harder than we already do. (Regular readers will remember I have floated a VAT before, and I want to revisit that idea honestly, warts and all.)
Then we will turn to the other side: what we actually spend money on, line by line, and who depends on each line. Every item in the budget has a constituency. It is one thing to say health care is a large share of federal spending; it is another to tell a specific group of people their benefits will be cut.
Mathematically, you can close the gap with tax increases, spending cuts, or a combination. Politically, you can’t do it with only one of those. That’s why we will likely not do anything substantial until a crisis forces our hand. Stay tuned…
Thanksgiving in Tulsa, Las Vegas, Cleveland, NYC and Austin
Shane and I will fly to Tulsa for Thanksgiving with the kids and lots of grandkids and family/friends next week. It is my favorite holiday of the year. We are flying in a few days early so I can shop, prep, cook and bake: I am the king of prime ribs, my mushrooms are to die for, a banana nut cake with my mother’s recipe, and so much more. Thanksgiving is my favorite day of the year. I know it is not just about feasting, and I have so much to be thankful for.
Then we will fly to Las Vegas for the largest longevity conference in the world December 10-13 and then I will fly to Cleveland for more procedures (nothing too serious, just annoying). I need to get into New York for a few days sometime in January or February, and then later in February we will be in Austin for an Inner Circle meeting.
Abbi has come through her brain surgery like a champ. She and her husband Stephen are driving back from Cleveland to Tulsa. She has to get out and stretch and move every hour and ½ or so, but they will arrive in Tulsa Saturday afternoon. Amazingly, she isn’t taking any of the pain meds they prescribed. She’s a better man that I am, Gunga Din. I can’t wait to see her next Wednesday.
And with that, I will hit the send button. You have a great week. Lord willing and the creek don’t rise, we will continue our thoughts on taxes and the rich next week. I truly hope your Thanksgiving is wonderful. You have a great week and don’t forget to follow me on X.
Your thinking about prime, turkey, mushrooms etc. and all my kids and grandkids analyst,
John Mauldin

Read important disclosures here.
YOUR USE OF THESE MATERIALS IS SUBJECT TO THE TERMS OF THESE DISCLOSURES.
If you like my letters, you'll love reading Over My Shoulder with serious economic analysis from my global network, at a surprisingly affordable price. Click here to learn more.
Put Mauldin Economics to work in your portfolio. Your financial journey is unique, and so are your needs. That's why we suggest the following options to suit your preferences:
-
John’s curated thoughts: John Mauldin and editor Patrick Watson share the best research notes and reports of the week, along with a summary of key takeaways. In a world awash with information, John and Patrick help you find the most important insights of the week, from our network of economists and analysts. Read by over 7,500 members. See the full details here.
-
Invest in longevity: Transformative Age delivers proven ways to extend your healthy lifespan, and helps you invest in the world’s most cutting-edge health and biotech companies. See more here.
-
Macro investing: Our flagship investment research service is led by Mauldin Economics partner Ed D’Agostino. His thematic approach to investing gives you a portfolio that will benefit from the economy’s most exciting trends—before they are well known. Go here to learn more about Macro Advantage.
Recent Articles
Why We Can’t Soak the Rich
November 20, 2026
Who Pays the Government’s Bills?
November 13, 2026
Debt Be Not Proud
November 6, 2026
When a Credit Default Swap Isn’t about Credit
October 30, 2026
AI: Where Will the Money Come From?
October 23, 2026
When Will AI Meet Cash Flow Reality?
October 16, 2026
Thoughts from the Frontline
Follow John Mauldin as he uncovers the truth behind, and beyond, the financial headlines. This in-depth weekly dispatch helps you understand what's happening in the economy and navigate the markets with confidence.
Let the master guide you through this new decade of living dangerously
John Mauldin's Thoughts from the Frontline
Free in your inbox every Saturday
By opting in you are also consenting to receive Mauldin Economics' marketing emails. You can opt-out from these at any time. Privacy Policy