

Thoughts from the Frontline
Follow John Mauldin as he uncovers the truth behind, and beyond, the financial headlines. This in-depth weekly dispatch helps you understand what's happening in the economy and navigate the markets with confidence.
Let John guide you through this decade of disruption
John Mauldin's Thoughts from the Frontline
Free in your inbox every Saturday
By opting in you are also consenting to receive Mauldin Economics' marketing emails. You can opt-out from these at any time. Privacy Policy
Latest Articles
March 5, 2013
An Infinite Amount of Money
The three major blocs of the developed world are careening toward a debt-fueled denouement that will play out over years rather than in a single moment. And contrary to some opinion, there is no certain ending. There are multiple paths still available to Europe and especially the US, though admittedly none of them are bright and carefree. There are very few paths available to Japan, as they have skipped too far down the yellow brick road of debt. None of Japan’s remaining paths have good endings. In the US, even as numerous voices declaim on the crisis that awaits if we don’t act, there is seemingly no collective will to actually do anything as yet. Perhaps it will take… a crisis. In Europe, the peripheral countries can already be said to be in crisis. This week we will look at the mindset that ignores warning signs, and reflect on a hard-to-believe comment from Mayor Bloomberg of New York. It is a teaching moment that does not bode well for my hopeful outcome in the US. Meanwhile in Europe, the risks have been heightened with the recent vote in Italy. We must remember that Italy is the world’s third-largest issuer of bonds – its problems matter on the world stage. While it may all be molto divertente for those of us sitting on the sidelines, the potential consequences are anything but amusing. But before we get going, if you are a qualified purchaser or an investment advisor in the US, I would like to invite you to listen in as I interview Jacob Gottlieb, CIO of Visium Asset Management, on Tuesday, March 26 at 12:00 p.m. EDT, 9:00 a.m. PDT. Visium is one of the premiere long/short multistrategy managers in the investment industry and of great interest to me. I will ask where they are finding alpha opportunities today, as well as share my own thoughts on the global economy and outlook. This discussion will be hosted by my partners at Altegris Investments. Please register for this exclusive webinar through The Mauldin Circle. If you are already a member of the Mauldin Circle and a qualified purchaser, you will receive an email invitation to the webinar. A replay will be available to registrants unable to attend. I apologize for limiting this discussion to qualified purchasers and investment advisors, but we must follow the rules and regulations. (In this regard, I am president and a registered representative of Millennium Wave Securities, LLC, member FINRA.)
February 26, 2013
The Healthcare Blues
It has been some time since we peeked into my worry closet. A few questions this weekend prompted me to think about things I am paying attention to but have not written about, and one thing that I am not worried about at all, despite the apparent media hysteria. But first, a quick note. My tenth annual Strategic Investment Conference (May 1-3 in Carlsbad, California) seems to be filling up nicely. The speaker lineup is exceptional: Kyle Bass; Ian Bremmer; Mohamed El-Erian; Niall Ferguson and his wife, Ayaan Hirsi Ali; Lacy Hunt; Charles and Louis Gave; Jeff Gundlach; Anatole Kaletsky; David Rosenberg; Nouriel Roubini; and Gary Shilling. Seriously, where else can you find a roster like that? And the attendee list has a “who’s who” feel to it, as well. Those who come regularly know that the real value is in meeting the other attendees. David Rosenberg noted last year that this is the top investment conference he has ever addressed. The speakers all seem to bring their “A” game. The attendees agree, and this year we will have more interaction than ever. The conference always sells out, and we offer an early-bird registration, which is about to run out. Because of security regulations, we do have to limit attendance to accredited investors and those in the securities/investment business. You can start the process by going to the Strategic Investment Conference page. But before we go any further, did you know that you can now absorb Thoughts from the Frontline through your ears, if your eyes are otherwise occupied? That’s right – our new audio service delivers my weekly letter to your cellphone, iPod, MP3 player, or computer, whenever and wherever you choose. You can check it out right here. And now, let’s peek into my worry closet.
February 19, 2013
Whatever It Takes
Lord Melchett: “Farewell, Blackadder [hands him a parchment]. The foremost cartographers of the land have prepared this for you; it's a map of the area that you'll be traversing. [Blackadder opens it up and sees it is blank] They'll be very grateful if you could just fill it in as you go along. Bye-bye.” – From the English comedy series Blackadder (Part 2, Episode 3) Was it only a few years ago I visited the Emerald Isle of Ireland? So recently had this fair land come to such a sad state. The collapse of its largest banks foreshadowed the demise of many other European banks that had borrowed money from British, German, and other European banks to lend against homes and property. The Irish government had to guarantee deposits and bond holders in order to prevent a bank run. I think I am correct when I state that the Central Bank of Ireland was the first central bank to avail itself of large-scale use of the Emergency Liquidity Assistance (ELA) provision of the European Central Bank. This was before we became so familiar with the process in Greece. The Irish banks had lost a combined €100 billion, borrowed largely from other European banks, which would also have incurred great losses had the Irish government not stepped in. You have to remember that this was before Greece and Spain needed assistance, although as Ireland stepped up to the table, the acronym “PIIGS” was coming into vogue; and some of us were writing about the debt problems that plagued Greece and other peripheral countries. The European Union compelled the Irish government to bail out its banks, and so the Central Bank of Ireland took on the debt (via the ELA) of the six main Irish banks that had failed because of the property bubble. In the “bailout,” Ireland received €67.5 billion (and in addition borrowed another €17.5 billion from its pension and cash accounts), which it pledged with a promissory note to pay back. The public was quite upset, and the government was then overwhelmingly rejected at the polls, in a clear show of sentiment demonstrating that the Irish people did not view that bank debt as something that should be on the public balance sheet. Government workers had to take large pay and pension cuts and government services were cut, as one of the conditions for getting the money was significant austerity. This was before “austerity” became a bad word in Europe. Meanwhile, unemployment rose from 4% to 14%. I visited Ireland after the new government took over. I met with some two dozen business leaders, politicians of all persuasions, journalists, and economists. I remarked at the time that the only thing they agreed upon was that Ireland would never pay that bailout money back. A former prime minister told me that they would not have to openly repudiate the debt, but rather were expecting, after Greece and other countries were allowed to default, to be invited not to pay it. A leading Irish economist who was at the negotiating table told me point-blank that the IMF negotiator told them they would not have to pay it back. But you have to remember that at the time there was true panic and no road map for dealing with such a crisis. Something had to be done. That something was the issuance of bailout funds (which conveniently minimized losses at said German, French, and British banks), which came with a private assurance to Irish leaders that whatever was done for other countries would be available to them as well. “But please, just work with us right now?” So the Irish, as we say in Texas, took one for the European team. The blow left a rather ugly scar, as the national debt ballooned into impossible-to-manage territory, crippling the national government. But there was one group in Ireland that was aghast – horrified – at the idea of not paying back that debt: those were the people I met at the Central Bank of Ireland. And they did have a point. The document that created the European Central Bank did not allow a national central bank to not pay its debts. Governments could default (as we learned with Greece), but not national central banks. Those were the rules that everyone who adopted the euro played by. At the time, I wrote that the Irish would not pay that debt. I had listened to the 99% of the people who told me so. Silly me. Yet, the last two weeks have seen the Irish convert their promissory note into government debt and agree to sell bonds. So it looks like the Irish will pay after all. Except that when you read the details, the Irish (after a great deal of controversy ensues) will end up either not actually paying or not paying anything close to the value of what they borrowed. So how can they both pay and not pay? That is the topic for this week’s letter; and an instructive reading it is, not for what it tells us about Ireland but for what it tells us about the EU, the eurozone, and the future of the euro.
February 12, 2013
How Not to Run a Pension
“The government is the prisoner of the bureaucracy. We have 4,021 associations and 6,200 codes. You simply cannot change things. There are 600,000 tax elements. No one really knows who pays what.” – A journalist in Greece For all the focus on the unfunded liabilities of Social Security and Medicare, there is another unfunded crisis brewing, and this one is in your own back yard. It’s coming to you even if you live outside of the US; it just might take a little longer to get there. I wrote ten years ago that state and local pension funds might be underfunded by as much as $2 trillion. It turns out that I was being overly optimistic. New government research suggests that the figure might be as high as $3 trillion. But what if you take into account that retirees are living longer? An IMF study that we’ll look at in a few minutes does just that. And if we live a lot longer? Oh my. The problems are not universal – some cities and states will do fine, while others are already in deep kimchee – but it’s a big problem and getting worse. At the end of the letter, I’ll add a personal note on housing. Longtime readers know that I was bearish on housing well before the bubble. I sold my home (for personal reasons) and decided to lease until things became more settled. I have said several times that I would tell you if and when I decided to buy a home. Now, I have put an offer in on an apartment and it has been accepted. But it’s more complicated than that. (Isn’t it always?) Before we get rolling, though, I want to announce the speaker lineup for my 10th annual Strategic Investment Conference, May 1-3. Here they are, in alphabetical order: Kyle Bass; Ian Bremmer; Mohamed El-Erian; Niall Ferguson and his wife, Ayaan Hirsi Ali; Lacy Hunt; Charles and Louis Gave; Jeff Gundlach; Anatole Kaletsky; David Rosenberg; Nouriel Roubini; and Gary Shilling. The noted geopolitical analyst Ian Bremmer (a professor at Columbia and founder of the Eurasia Group) has now been added to the list. I heard Ian last year speak on his theme of a G-Zero World and was blown away. You have to hear this one. We subsequently met in NYC and compared notes. I am really happy we could get him. Seriously, where else can you find a roster like that? And the attendee list has a “who’s who” feel to it, as well. Those who come regularly know that the real value is in meeting the other attendees. David Rosenberg noted last year that this is the top investment conference he has ever addressed. The speakers all seem to bring their “A” game. The attendees agree, and this year we will have more interaction than ever. The conference is cosponsored by my longtime partner Altegris Investments. All the credit for hosting a first-class conference goes to the staff at Altegris, who do a massive amount of work to pull off an event of this size and scope. All I do is get a few friends to come and speak. Oh, and this year Bloomberg will cover the conference live. The conference always sells out, so I suggest you register at your earliest convenience. Invitations have been sent out to past attendees and those who are members of the Mauldin Circle. Registration is now open. Because of security regulations, we do have to limit attendance to accredited investors and those in the securities/investment business. You can start the process by going to the Strategic Investment Conference page. There is a significant early-bird registration discount.
February 5, 2013
The Good, the Bad, and the Greek (Risks)
“The euro will not survive the first major European recession.” – Milton Friedman, 1999 “It seems to me that Europe, especially with the addition of more countries, is becoming ever-more susceptible to any asymmetric shock. Sooner or later, when the global economy hits a real bump, Europe’s internal contradictions will tear it apart.” – Milton Friedman, 1999 “… there will be asymmetric shocks hitting the different countries. That will mean that the only adjustment mechanism they have to meet that with is fiscal and unemployment: pressure on wages, pressure on prices.” – Milton Friedman, 1998 “Barry Eichengreen (1990b), in a detailed analysis of the potential lessons for EMU from the U.S. experience, concluded that monetary integration would limit fiscal independence. He argued that the extent of fiscal transfers in the European Union would have to significantly exceed the extent of fiscal transfers in the United States to be successful, as regional shocks were likely to be significantly greater in EMU countries than in the states of the United States.” – From a lengthy (and exhausting) paper at the Econ Journal Watch, analyzing the writing of scores of US economists about the euro from 1989-2002. The paper was humorously titled “It Can’t Happen, It’s a Bad Idea, It Won’t Last: U.S. Economists on the EMU and the Euro, 1989-2002.” Greece was (and is) the first real test of the euro. Until the Greek crisis, there was no real need for any eurozone country to actually write a check for any other member. Ireland obligingly shouldered the responsibility for its own bad bank debts, paying off mostly German, French, and British bankers. But Greece required someone else to take the losses and write the checks to bail the country out. The European Central Bank had to agree to allow the Bank of Greece to create euros to bail out its banks (with the fig leaf that somehow Greece will pay them back). As the Greek economy collapsed in the aftermath of the recent crisis, it became evident even to European bankers and regulators that Greece could not pay its debt. Money began to flee Greek banks. Greece is a small country with large implications. Last week we began to explore what I learned from my recent trip to Greece. In this week’s letter we will finish those observations and in particular look at some of the comments from my meetings with over 40 people: owners of small businesses and large ones, billionaires, taxi drivers, politicians, central bankers, investors, ex-patriots, wives, and mothers. I believe we can arrive at some small understanding of the problems Greece faces. Then we will consider the broader consequences for Europe.
January 24, 2013
Prisoner of the Bureaucracy
I wrote some time ago that Greece had a choice between Disaster A: staying in the euro; and Disaster B: leaving the euro. I have recently come back from four days in Greece, meeting with lots of people at all levels of society, and will share with you in this letter my analysis of their choices and the results. I’ll also have a few things to say about what the developments in Greece might mean for the rest of Europe and the developed world. I penned these words in January of 2010: “Everyone knows the problems of Greece. There is no political will in the country (so far) to do what Ireland has done, and really cut their budget. I think Spain is an even bigger nightmare for the EU when compared to relatively small Greece. Italy? Belgium? Portugal? All those countries (and their voters) will be watching to see how the EU deals with Greece.” Which was good for Greece, as it gave good reason for the rest of Europe to care about what happened to Athens.
January 13, 2013
Forecast 2013: Unsustainability and Transition
“There are decades when nothing happens and there are weeks when decades happen.” – Vladimir Ilyich Lenin "People only accept change when they are faced with necessity, and only recognize necessity when a crisis is upon them." – Jean Monnet "If something cannot go on forever, it will stop." –Herbert Stein As we begin a new year, we again indulge ourselves in the annual (if somewhat futile) rite of forecasting the year ahead. This year I want to look out a little further than just one year in order to think about the changes that are soon going to be forced on the developed world. We are all going to have to make a very agile adaptation to a new economic environment (and it is one that I will welcome). The transition will offer both crisis and loss for those mired in the current system, which must evolve or perish, and opportunity for those who can see the necessity for change and take advantage of the evolution. This is my most-read letter of the year, by the way, and if you’re not yet a subscriber you can join my “one million best friends” and receive both Thoughts from the Frontline and my other weekly letter, Outside the Box, as well as Grant Williams’ rollicking Things That Make You Go Hmmm…, all for free, by simply entering your email address on my site: http://www.mauldineconomics.com/go/bwbsl/MEC
December 30, 2012
Somewhere Over the Rainbow
We are 13 years into a secular bear market in the United States. The Nasdaq is still down 40% from its high, and the Dow and S&P 500 are essentially flat. European and Japanese equities have generally fared worse. The average secular bear market in the US has been about 11 years, with the shortest to date being four years and the longest 20. Are we at the beginning of a new bull market or another seven years of famine? What sorts of returns should we expect over the coming years from US equities? Even if you have no investments in the stock market, this is an important question, in part because the pensions funded by state and local governments are heavily invested in US equities. In fact, they are often projecting returns in excess of 10% per year. How likely is that to happen? Who will make up the difference if it doesn’t? In nearly all states and jurisdictions, it is against the law to change the terms of a public pension plan once it is agreed upon. Even more important to you personally, what will happen to your taxes if the secular bear persists? On this final day of 2012, let’s take a look at the potential returns of the stock market over the next 7-10 years. In previous Thoughts from the Frontline and in my book Bull’s Eye Investing, I have written that stock market returns are a function of valuations (typically, price-to-earnings ratios). Secular bull markets are periods of rising valuations, while secular bear markets are periods of falling valuations. While stock market returns can vary widely over one-year, ten-year, or twenty-year periods, over the long term stock market earnings have tended to correlate very highly with GDP and inflation. Since GDP has tended to grow (at least until recently) at 3% per year, predicting long-term returns and secular bull and bear markets has been pretty straightforward. But recently several noteworthy analysts have presented research suggesting that GDP will not grow anywhere close to 3% over the coming decades. In today’s letter we look at the ramifications of slower GDP growth on equity returns. For most investors this is a very important topic, as the stock market tends to be the main driver of their investment returns.
December 23, 2012
Looking on the Bright Side
It is Christmas Eve and not the time for long letters – just a brief note on why the fiscal cliff is not the End of All Things, and to point out a worthy cause led by some good friends of mine who are helping people who truly have no options in life. And we’ll start things off with a movie review of sorts to launch us into a positive take on the year behind and the year ahead.
December 16, 2012
Central Bank Insurance
“For every complex problem there is an answer that is clear, simple and wrong.” – H. L. Mencken Possibly, the question I am asked the most is, “What do you think about gold?” While I have written brief bits about the yellow metal, I cannot remember the last time I devoted a full e-letter to the subject of gold. Longtime readers know that I am a steady buyer of gold, but to my mind that is different from being bullish on gold. In this week’s letter we will look at some recent research on gold and try to separate some of the myths surrounding gold from the rationale as to why you might want to own some of the “barbarous relic,” as Keynes called it. My personal reasons for owning gold have evolved over the years. I will tell you the story of my own journey, and you can decide for yourself whether to think about coming along. I cannot start this letter, however, without a brief but sad note about the tragic events at Newtown. As a parent I cannot imagine the anguish and horror at learning that my child was murdered while sitting in her first-grade classroom. The senseless wasting of so many young lives leaves me profoundly saddened for our country and culture. There is not much that I can say other than to extend my deepest sympathies to the families and friends of the victims – and perhaps to wonder about the wisdom of relegating violence to the level of an arcade game in the movies and games our kids watch and play.
December 9, 2012
Peak Oil or Peak Energy? – A Happy Solution
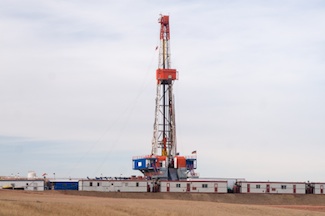
A consistent theme in this letter has been the connections between items that may seem to be far removed from each other but are actually linked at the very core. If you push on one end you get a reaction in what would seem to be the most unlikely spots. Today we explore the connection between the fiscal deficit and energy policy. Everyone in Washington is starting to “get religion” about wanting to fix the deficit, with serious thinkers on all sides acknowledging that there must be reform and a path to a balanced budget. Burgeoning healthcare and Social Security costs are rightly pointed to as the problem, and entitlement reform will soon be front and center. But the fiscal (government) deficit in the US cannot go away unless we also deal with the trade deficit. As we will see, it is a simple accounting issue, and one based on 400 years of accepted accounting principles. And dealing with the trade deficit in the US means working with our energy policy. The trade imbalances among the partners in the eurozone are at the heart of the problems there as well. And while we will get back to Europe in a few weeks (remember when we seemed to be focused on Europe and Greece for months on end?), today we will explore the trade problem from a US perspective. Happily, this problem, while serious, does have a workable solution. And it might even happen in spite of government policy, though if a proactive energy policy were developed, it could ignite a true economic renaissance. I have been wanting to explore the implications of the shale oil revolution. Old oil fields are wearing out, as peak oil advocates point out. Where can we find the huge and cheap-to-exploit oil fields to replace them? Hasn’t all the easy oil already been found? We will start in the Texas of my youth, journey to North Dakota where I was last week, and then think about the implications of that journey. There are many connections and interesting paths to explore. The letter will print a little long, as there are a lot of charts.
November 25, 2012
Capital Formation and the Fiscal Cliff
In today’s economic environment, we often complain about volatility and uncertainty, but there is one thing I think we can be fairly certain of: taxes are going up. I constantly try to impress upon my kids, most of whom are now adults, that ideas and actions have consequences. In today’s letter we will look at some of the consequences of an increase in taxes. Please note that this is different from arguing whether taxes should rise or fall. For all intents and purposes that debate is over. As investors, our job is to deal with reality. We must play the hand we are dealt. Taxation is a complex issue, but let’s see if a few word pictures can help us understand what we face. Two quick notes to begin with. The full video interview with David Krone and Rob Lehman, the chiefs of staff for Senate Majority Leader Harry Reid (D-NV) and Senator Rob Portman (R-OH), two of the key figures in the current budget negotiations, is now available online. This was not a debate but a thoughtful exchange of ideas and positions that occurred as part of our recent Post-Election Economic Summit. It is helpful to recognize that negotiations over the fiscal cliff were being conducted weeks before the election. Everyone knew what was coming, and the very professional staffs that are charged with coming up with a reasonable resolution to the issue were already hard at work, knowing that there would be a lot still to do after the election. Krone and Lehman are two men at the very center of that debate. If you want to get some real insight into the congressional process, this is an excellent way to do it. I’m grateful that they agreed to sit down for this rather unprecedented sort of interview. You can watch the full interview. You can also view an edited version of the entire Post Election Summit, with Mohamed El-Erian, Dr. Gary Shilling, Rich Yamarone, Barry Ritholtz, Jim Bianco, Barry Habib, and myself. It has been getting rave reviews, and I trust it will be worthy of your time. I’m also pleased to announce that my very good friend Dr. Lacy Hunt has agreed to do a special Fireside Chat with me on December 4. Regular readers of Outside the Box are quite familiar with Lacy. As always, we will cover a wide variety of topics, but I’ll make a point of getting his views on where the economy will be going for the next few years. Lacy is one of the finest economists I know. I am always amazed at the breadth of his knowledge and the depth of his insight. This webinar will be available to members of the Mauldin Circle. If you have already joined, you will get a notice of the event details. If you have not yet joined, you can go to www.mauldincircle.com. This webinar is sponsored by my partners at Altegris Investments and is for accredited investors. (In this regard I am president and a registered representative of Millennium Wave Securities, LLC, member FINRA.) Now, shall we dive off the fiscal cliff?
- Page 58
Free Financial Newsletter
Thoughts from the Frontline explores developments overlooked by mainstream news and analyzes challenges and opportunities on the horizon.
The newsletter began as John’s way of sharing his thoughts with a few associates. Two decades later, it is one of the most widely read investment newsletters in the world. From his warning of an impending recession in 2000, to a polemic on the Obamacare “death spiral” in 2016, John has blazed his own trail as one of the most respected macroeconomic minds in the field.
"Central bankers, businessmen, and investors continually try to beat History to a pulp, but History always wins the final rounds."
John Mauldin, Thoughts from the Frontline, 2001.



John Mauldin
Editor, Thoughts from the Frontline
When investors, financial professionals, and discerning citizens need a big-picture view of what's going on in the economy, they turn to John Mauldin.
And for good reason. John has dedicated more than 30 years to keeping people informed about financial risk.